This has been a year packed with history-making moments on Wall Street. We've watched the Dow Jones Industrial Average (^DJI -0.34%), S&P 500 (^GSPC -1.09%), and Nasdaq Composite (^IXIC -2.15%) climb to several record highs, and witnessed the largest initial public offering in the stock market's storied history.
Perhaps the most defining moment of 2026 is the changing of the guard at our nation's central bank. On May 22, Kevin Warsh officially succeeded Jerome Powell as Fed chair. President Donald Trump's nominee to replace Powell has wasted little time reforming the Federal Reserve.
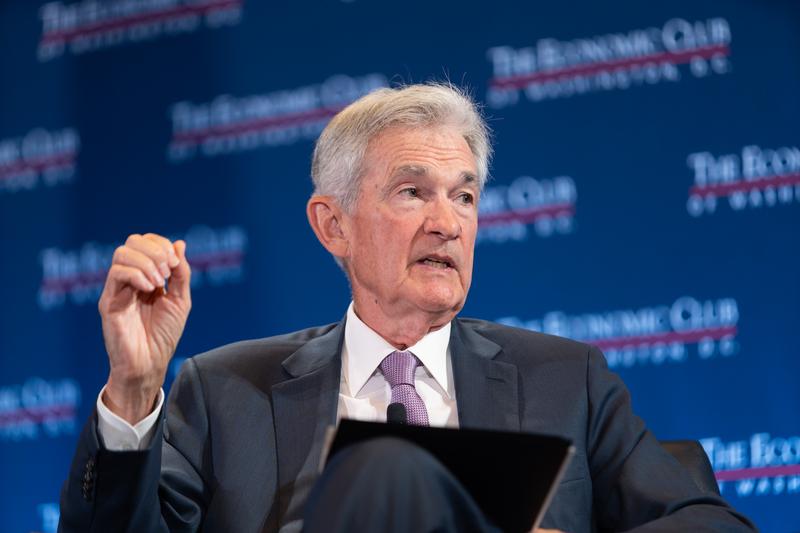
Jerome Powell waded into a subject rarely touched on by Fed chairs. Image source: Official Federal Reserve Photo.
But even though Powell is no longer head of the central bank — he remains on the Board of Governors of the Federal Reserve — his words still hold plenty of weight on Wall Street. More than a year after delivering a speech in Rhode Island, a six-word statement from the now-former Fed chair echoes louder than ever through Wall Street.
During Powell's two terms as Fed chair, he delivered dozens of speeches and fielded countless questions from reporters. It was rarely a challenge for the press to get Powell to discuss the labor market or touch on the catalysts affecting inflation.
However, one subject that sitting Fed chairs rarely discuss is stock valuations. The head of the central bank doesn't want to be responsible for influencing equity markets. This is something we've repeatedly witnessed from current Fed Chair Kevin Warsh, who's shied away from offering forward-looking guidance in any form.
Kevin Warsh just ended his first ever FOMC meeting as Fed chair. His message to markets: "I can't give you any guidance on what we're going to do next." Here is what he said: 1. Inflation is still way above the Fed's 2% target and prices are too high for most people 2. "We will fix five years of misses on inflation", he is directly saying the previous Fed failed 3. The Fed will no longer tell you in advance what it plans to do with interest rates 4. He watches stock market prices more than anything else when making decisions 5. Interest rates are hurting the housing market but are not slowing down financial markets 6. All 19 members at the table agreed not to raise rates today 7. The 2% inflation target is not changing 8. He refused to say whether bond yields rising after today's decision concerns him 9. He refused to say whether he has spoken to Trump since becoming Fed chair Under Powell, the Fed always told markets what was coming next. Under Warsh, that is gone.
But once in a blue moon, a sitting Fed chair will weigh in on equity valuations, if and only if those valuations somehow pose a threat to the integrity of credit markets and/or the health of the U.S. economy, including the job market.
In December 1996, then-head of the central bank, Alan Greenspan, delivered what became known as the "irrational exuberance" speech at the American Enterprise Institute. Greenspan's speech covered the rapid rise in stock valuations amid the advent and proliferation of the internet.
In September 2025, Powell had a mini-Greenspan moment. While responding to a reporter's question about how the Fed accounts for equity valuations in monetary policy, Powell offered a rare observation about stock valuations:
This six-word response, "equity prices are fairly highly valued," is a warning shot fired across the bow of Wall Street.
While game-changing technologies, such as the internet, have previously supported premium stock valuations for a few years, history says that extended valuations aren't sustainable over the long run.
Image source: Getty Images.
Given that there isn't a one-size-fits-all blueprint to value individual stocks or the broader market, valuation is one of the trickiest subjects to discuss. Even Alan Greenspan's irrational exuberance speech was, in hindsight, delivered more than three years before the dot-com bubble burst in March 2000.
There is, however, one time-tested valuation tool that's done a remarkable job of providing investors with apples-to-apples valuation comparisons of the S&P 500. More importantly, this valuation tool has a knack for foreshadowing short-term directional moves in the Dow Jones Industrial Average, S&P 500, and Nasdaq Composite. I'm talking about the S&P 500's Shiller Price-to-Earnings (P/E) Ratio, also known as the Cyclically Adjusted P/E Ratio (CAPE Ratio).
What helps the Shiller P/E Ratio stand out is that it factors in trailing earnings over the previous decade. Whereas the traditional P/E, which uses trailing 12-month earnings, can be tripped up by recessions if earnings turn negative, this isn't a concern for the Shiller P/E Ratio.
Introduced by economists in 1988, the CAPE Ratio has been back-tested to January 1871. Over the last 156 years, it's averaged a multiple of 17.42. As of the closing bell on Oct. 12, this valuation tool was approaching a multiple of 42, just a stone's throw away from its all-time high of 44.19, set just three months before the dot-com bubble burst.
Stock Market Shiller PE Ratio on the verge of taking out its Dot Com Bubble all-time high 🚨 🤯 👀 https://t.co/CtCmSgWnLt
Over the last century, the Shiller P/E has surpassed 30 during a continuous bull market on six occasions, including the present. The previous five occurrences all eventually saw the Dow Jones Industrial Average, S&P 500, and/or Nasdaq Composite plunge between 20% and 89%. For instance, the S&P 500 and Nasdaq shed 49% and 78% of their respective values on a peak-to-trough basis after the dot-com bubble burst.
While the S&P 500's CAPE Ratio has an uncanny ability to foreshadow what's next for stocks, it offers no help in pinpointing precisely when the music will stop or which catalysts will push stocks over the proverbial cliff. Nevertheless, Jerome Powell's six-word warning about equity prices is historically spot-on.
The one thing to always keep in mind is that while historical precedent can offer dire short-term forecasts, history is an undeniable ally of patient, optimistic investors. Looking back more than a century, there hasn't been a rolling 20-year period in which Wall Street's benchmark index has delivered a negative average annual total return, including dividends.
If former Fed Chair Jerome Powell's stock valuation warning proves prescient, consider it an opportunity to pounce on great companies at bargain prices.
Sean Williams has no position in any of the stocks mentioned. The Motley Fool has no position in any of the stocks mentioned. The Motley Fool has a disclosure policy.
*Average returns of all recommendations since inception. Cost basis and return based on previous market day close.
Invest better with The Motley Fool. Get stock recommendations, portfolio guidance, and more from The Motley Fool's premium services.
Making the world smarter, happier, and richer.
© 1995 – 2026 The Motley Fool. All rights reserved.
Market data powered by Xignite and Polygon.io.
About The Motley Fool
Our Services
Around the Globe
Free Tools
Affiliates & Friends
Jerome Powell boldly went where few Fed chairs have gone before.
About the Author