This is a secure area and requires you to be logged in to the Members’ Zone.
My organisation has an SMMT membership and I have an account
My organisation has an
SMMT membership and I need to register for an account
I am not part of an organisation that has an SMMT membership
The UK and European Union must strengthen cooperation on trade, batteries and critical raw materials to protect their automotive industries in the face of geopolitical challenges and reap the opportunity of deeper strategic cooperation, according to a new report from LSE Consulting.
The report, Strategic Cooperation: UK–EU Automotive Value Chains Amid Global Challenges, finds that the global automotive industry’s focus is shifting towards China, while manufacturers in the UK and Europe face mounting pressures from the transition to electric vehicles, geopolitical competition and rising production costs.
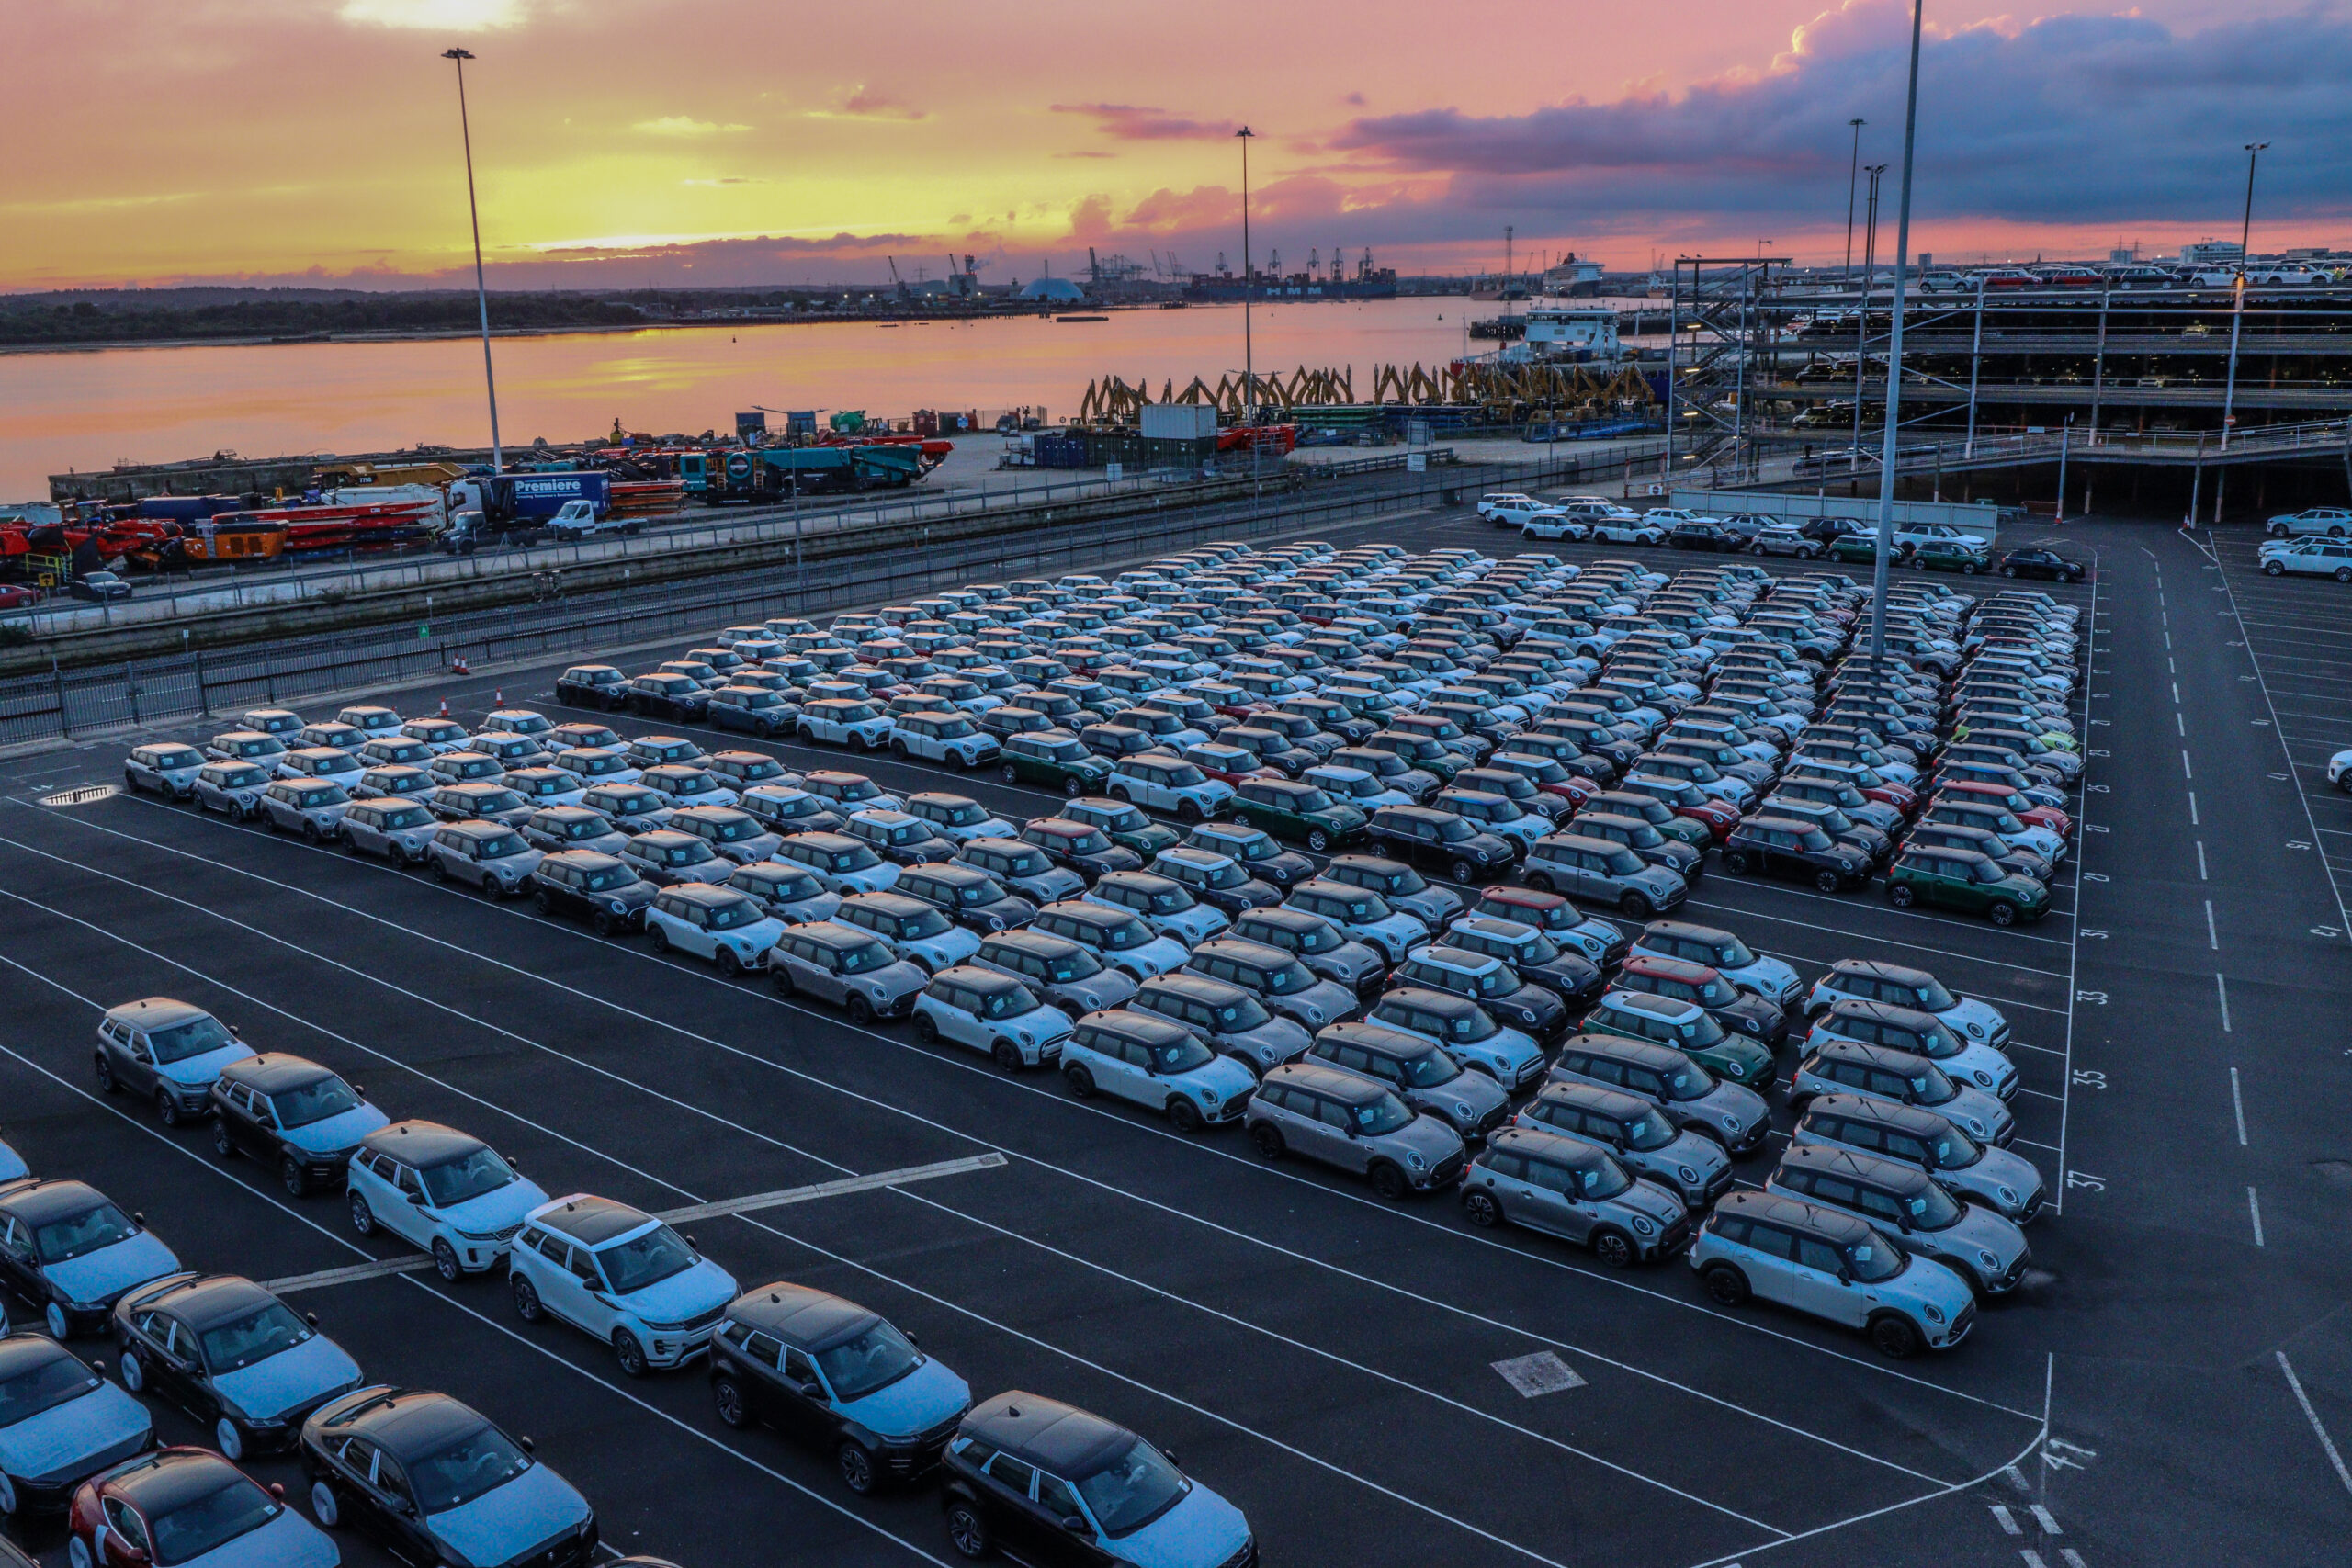
The research argues that, although these challenges are driven by global developments, the closely integrated EU-UK automotive relationship remains one of the most important levers available to policymakers to strengthen the industry’s competitiveness and resilience. The two markets are each other’s top automotive trading partners, and the UK is the EU’s largest parts export market, ahead of the US and China. Deeper cooperation and coordination can turn this relationship into a strategic asset to help both sides secure future investment, jobs and industrial leadership in the transition to electric vehicles.
This report shows why decisions taken on either side of the Channel affect firms, workers and suppliers on the other, and why a more coordinated approach is in both sides’ interests. The policy debate is moving quickly, often faster than the evidence available to inform it.
“Our contribution is to use data to show more clearly the scale and structure of these interdependencies, and the risks of treating the two systems separately. At this point in the evolution of EU–UK relations, stronger evidence is essential to designing policies that support investment, resilience and competitiveness across the wider European automotive sector.
The report identifies dependence on batteries and critical raw materials as one of the most significant shared vulnerabilities. Despite an estimated €72 billion invested in European battery and electric vehicle manufacturing facilities since 2017, the EU still imports around two-thirds of the lithium-ion batteries it uses, while the UK has a smaller domestic battery manufacturing base.
This poses an immediate challenge ahead of changes to the rules of origin under the UK-EU Trade and Cooperation Agreement (TCA), due to take full effect on 1 January 2027. The report warns that neither side can assume it will have sufficient battery supply that meets the requirements to avoid tariffs by 2027. With the UK the EU’s largest battery electric vehicle (BEV) market, the issue should be treated as a shared challenge for both the EU and UK, with firms warning of potentially substantial additional costs if no mitigation is agreed.
Drawing on firm-level data covering 62 automotive business groups between 2014 and 2024, a survey of businesses across the automotive value chain, and interviews with industry executives and policymakers, the report sets out recommendations for a more coordinated UK-EU response.
The report’s recommendations include:
The report argues that these measures should support the transition to lower-emission vehicles while giving manufacturers the predictability they need to invest. It also calls for closer regulatory alignment where EU-UK divergence creates additional costs without clear strategic benefits.
The report concludes that a coordinated partnership on trade, critical minerals and batteries is the clearest priority emerging from the industry’s evidence. Without greater cooperation, both markets risk becoming more dependent on external suppliers and losing ground in manufacturing and technological innovation.
The report was prepared by the Trade Policy Hub, part of LSE Consulting, for the European Automobile Manufacturers’ Association (ACEA) and the Society of Motor Manufacturers and Traders (SMMT).
The close ties between the EU and UK automotive industries are a strength we cannot afford to undermine. Both sides have a shared interest in building on this relationship to create the right conditions for investment, innovation and manufacturing. Closer cooperation and pragmatic policy choices will be key to ensuring Europe excels as a competitive place to build and sell vehicles.
The UK and EU are bound by €80 billion in annual automotive trade and millions of jobs. At a time of intense global competition, this report makes clear the need for both sides to collaborate and remove barriers to trade. Our collective response must strengthen both sectors, with the UK included in ‘Made in Europe’ measures, a pragmatic solution to 2027 rules of origin, and stronger integrated supply chains. Get this right and we can attract investment, safeguard jobs and drive growth on both sides.
Notes to editors
Strategic Cooperation: UK–EU Automotive Value Chains Amid Global Challenges was delivered by an academic team with expertise on trade, foreign direct investment, global value chains and economic security, showcasing the interdisciplinary work of the Hub.
The report combines novel quantitative analysis of 62 automotive business groups with a survey of firms and interviews with industry executives and EU and UK officials, to provide policy-relevant insights.
Sign up to the SMMT Update Newsletter for weekly automotive news and data
"*" indicates required fields
SMMT is the voice of the UK motor industry, supporting and promoting its members’ interests, at home and abroad, to government, stakeholders and the media.
The Society of Motor Manufacturers & Traders,
71 Great Peter Street,
London, SW1P 2BN
About the Author